A useful budget is not a prediction that must be perfectly correct. It is a plan for making trade-offs before your money disappears into dozens of small decisions. The best budget gives every important expense a place while leaving enough room for real life to happen.
If you have abandoned budgets because one unexpected bill ruined the month, the problem may not be your discipline. The plan may have been too rigid. A flexible budget uses priorities, ranges, and regular check-ins instead of treating every category as a fixed promise.
Start With Your Financial Floor
Your financial floor is the minimum amount required to keep life stable. List housing, basic groceries, utilities, transport, insurance, minimum debt payments, and essential care. Use recent transactions rather than memory, because irregular charges are easy to overlook.
- Review at least the last two full months of transactions
- Separate essential costs from optional upgrades
- Convert annual or quarterly bills into monthly amounts
- Keep a small margin for price changes
This number is not your entire budget. It is the protected base that helps you understand how much of your income is already committed.
Choose Priorities Before Percentages
Popular rules such as 50/30/20 can be useful starting points, but they are not universal laws. Housing costs, family responsibilities, income stability, and debt can make a standard percentage unrealistic. Start with the outcome you need most: a starter emergency fund, clearing expensive debt, or saving for a known expense.
Give that priority a specific monthly amount. What remains can be divided between flexible spending and lower-priority goals. This order makes the budget reflect your life instead of forcing your life into a template.
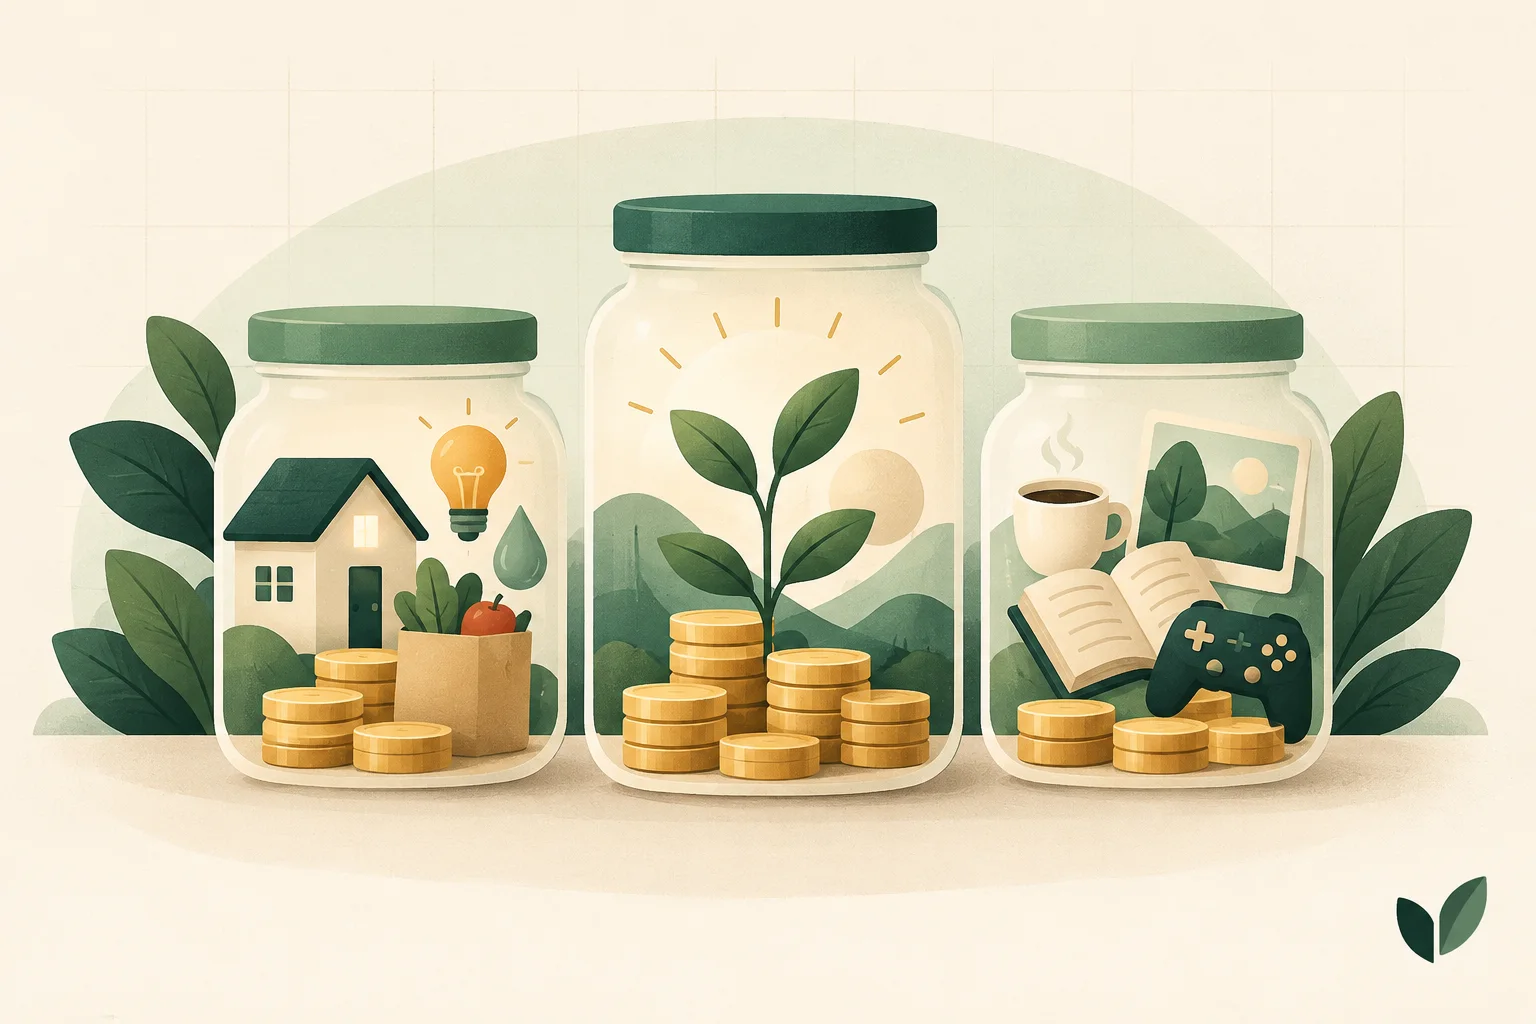
Use Three Practical Buckets
- Essentials: the financial floor and minimum commitments
- Goals: savings, additional debt payments, and planned future costs
- Flexible spending: dining, hobbies, shopping, and other adjustable choices
You can create more detailed categories later, but these three buckets make the first version easy to maintain. When an expense changes, adjust within the relevant bucket before taking money from a protected goal.
Plan for the Expenses That Are Not Monthly
A car service, school payment, annual subscription, or holiday is not an emergency when you know it will happen. Estimate the amount and due date, then set aside a portion each month. These small reserves prevent predictable costs from competing with rent or savings later.
Check the Plan Weekly, Not Constantly
A short weekly review is frequent enough to catch drift without turning money management into a daily chore. Look for categories that are moving faster than expected, confirm upcoming bills, and decide one adjustment for the next week.
- Move money between flexible categories when priorities change
- Reduce the next week's discretionary spending after an unusually expensive week
- Keep savings automatic unless a genuine essential needs attention
- Record what changed so next month's plan starts with better information
Use MoneyMori as the Feedback Loop
In MoneyMori, Wallets show where money lives, Transactions show where it goes, and Budgets turn that activity into limits you can monitor. Start with a few broad Categories, add the transactions you want to understand, and review the Report to compare the plan with reality.
The goal is not a month with zero surprises. It is a system that helps you respond to surprises without losing sight of what matters. A budget that bends is more likely to survive—and a budget you keep using is far more valuable than a perfect one you abandon.