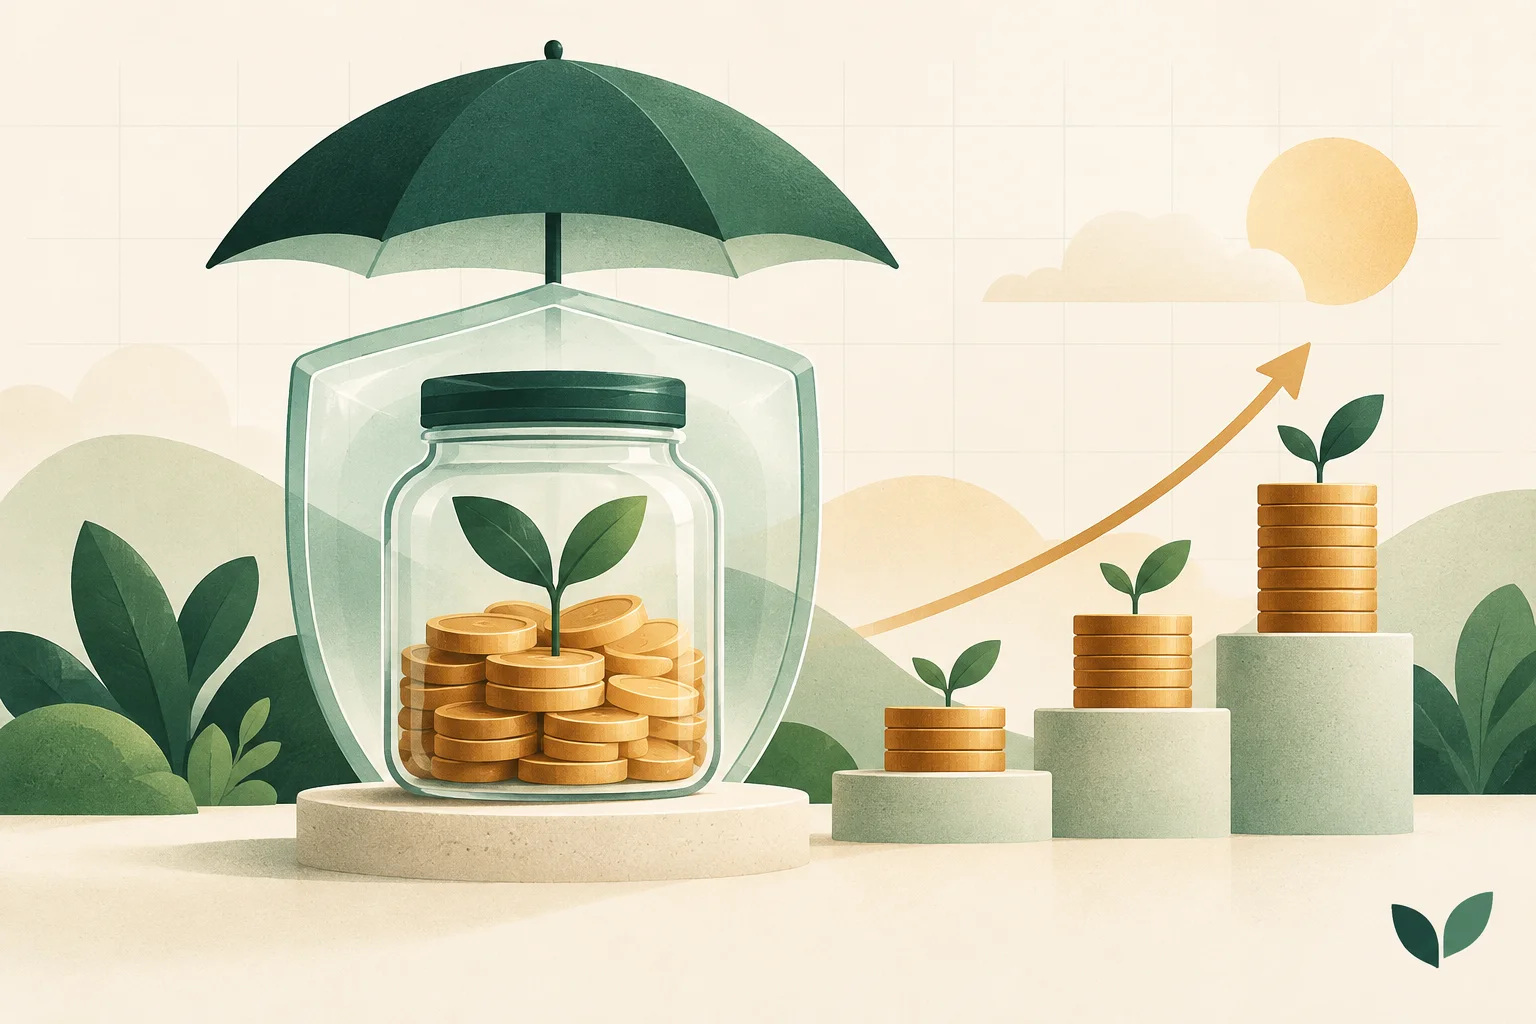
An emergency fund gives you time to make a good decision when life becomes expensive without warning. It can cover an urgent repair, necessary medical cost, or a gap between jobs without immediately turning the problem into high-interest debt.
The phrase “three to six months of expenses” is useful, but it can feel impossible when you are starting from zero. Build the fund in stages. Each milestone solves a different problem and makes the next one easier to reach.
Milestone 1: Protect One Common Surprise
Choose an initial amount that can cover a common urgent expense in your life. That might be a medical visit, a necessary device replacement, a basic vehicle repair, or urgent travel. The right first milestone is large enough to matter and small enough to reach within a few months.
Keep this money separate from everyday spending. It should be accessible, but not so visible that it feels available for routine purchases.
Milestone 2: Cover One Month of Essentials
Add up the expenses you must pay to keep your household functioning: housing, basic food, utilities, transport, insurance, minimum debt payments, and essential care. Do not use your full normal spending total. An emergency month usually removes optional spending.
- Use recent bills and Transactions instead of guessing
- Include non-monthly essentials as a monthly average
- Exclude optional subscriptions and discretionary shopping
- Review the total when rent, family needs, or debt payments change
One month of essentials can absorb a delayed payment, a short income gap, or several smaller surprises arriving together.
Milestone 3: Match the Fund to Your Risk
After one month, choose a longer-term target based on how quickly your income could recover. A household with two stable incomes may need a smaller buffer than a freelancer with variable clients or a sole earner supporting dependents.
- Consider a larger target when income is irregular
- Add room when you support children, parents, or other dependents
- Account for health, home, or transport costs that are hard to postpone
- Use a smaller target only when other reliable resources are genuinely available
Make Contributions Automatic and Visible
A small automatic transfer after payday is more dependable than waiting to see what remains at the end of the month. Start with an amount you can repeat. Increase it after a debt payment ends, income rises, or a regular expense falls.
Windfalls can accelerate the plan, but they should not be the only plan. Consider directing part of a bonus, refund, gift, or sale of unused items to the fund while keeping a portion for another priority.
Define What Counts as an Emergency
Use the fund when an expense is necessary, urgent, and unplanned. A discounted purchase can be unexpected without being necessary. A yearly bill can be necessary without being unplanned. Clear rules protect the fund from slowly becoming another spending Wallet.
Track the Goal in MoneyMori
Create a Goal for each milestone and record contributions as you make them. Review your essential Categories when calculating the target, and keep the saved money in a Wallet that is separate from daily spending. Progress becomes easier to trust when the target, current amount, and activity are visible together.
If you use the fund, that is the system working—not a failure. Pause, handle the emergency, then make replenishing the fund your next savings priority. The purpose of the money is resilience, and resilience includes rebuilding.